-
цена: $0.10095 1.9375%
-
Рыночная стоимость: 15.75B 0.5365%
-
Оборот (24h): 2.12B 0%
-
Dominance: 0.5365% 0.5365%
-
цена: $0.10095 1.9375%

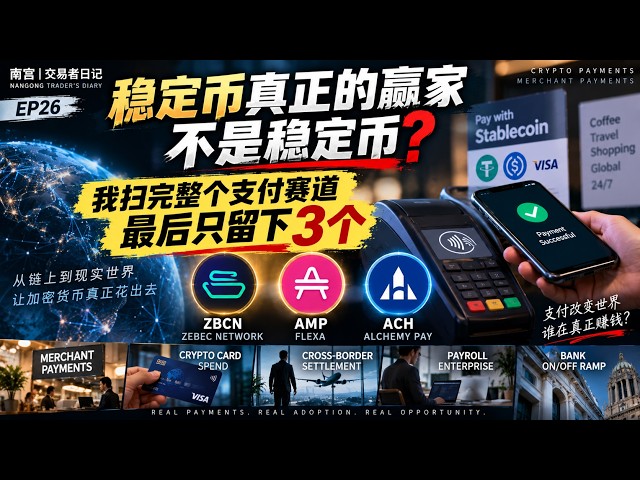
Isn’t the real winner of stablecoin stablecoin? I swept through the entire payment track, leaving only 3 in the end|ZBCN, AMP, ACH|EP26
выпускать: 2026/09/23 12:10 читать: 0
Оригинальный автор:南宫交易日记
Первоисточник:https://www.youtube.com/embed/7NDmueL_qHE
💳 **EP26|Crypto Payments / Merchant Payments** Stablecoins have become more and more like real “money”. But the bigger question is: **How is this money actually spent? ** How to access bank card? How to let merchants collect payment? How to make cross-border settlement? How to pay wages? How to connect bank account? And who provides liquidity and settlement guarantees before payments are completed? This is what we are studying in this issue: # 💰 Crypto Payments / Merchant Payments In this issue, I will not discuss: **Who is stronger, USDT or USDC. ** Instead, continue to go downstream in the payment industry chain: **Stablecoin → Payment → Card → Merchant → Settlement → Bank** Let’s take a look at the projects that actually undertake these payment scenarios. ━━━━━━━━━━━━━━ ## 🌍 Stablecoin payment is no longer a concept. Traditional payment giants such as Visa, Mastercard, and Stripe have begun to integrate stablecoins into real payment and settlement networks. Stablecoins are gradually entering: 💳 Bank card consumption 🏪 Merchant collections 🌎 Cross-border payments 💼 Corporate payments 💰 Payroll 🏦 Bank accounts 🔄 On / Off-ramp ⚡ 24/7 Settlement So the real question in this issue is no longer: **"Will stablecoin payments happen?"** but: ### **"After stablecoin payments really explode, who can make money?"** And more importantly to Crypto investors: ### **"Will the money finally return to the Token we can buy?"** ━━━━━━━━━━━━━━ # 🔍 First level: Full track scan In this issue, we scanned multiple directions in the payment industry chain: ### Merchant Acceptance How do merchants accept Crypto/Stablecoin? ### How can Card / Spend users directly transfer money on the chain? ### Settlement How to clear cross-border payments and bank cards? ### Bank / Fiat Bridge How to connect a bank account to on-chain funds? ### Payment Financing Who will provide funds before the payment has completed final settlement? We have studied and compared different payment-related projects including: ZBCN HUMA XPL TEL AMP ACH REQ STABLE and XLM, XRP, GNO, ETHFI, CRO, DASH, etc. Key data are cross-verified using official information, on-chain data and multiple independent third-party sources. ━━━━━━━━━━━━━━ # ❌ Why are many well-known projects eventually eliminated? Because in this issue we are not looking for: **"Who is most like a payment project."** But we are looking for: **"After the payment business really grows, can Token be forced to gain more demand?"** So: Some projects have good business, but Token capture is too weak; some projects have beautiful Tokenomics, but the real payment volume cannot be verified; some projects have good products, but FDV and future unlocking pressure are too great; and some projects, there is no direct economic connection between the company making money and the Token Holder. This is also where Crypto Payments is most prone to misunderstandings. ━━━━━━━━━━━━━━ # 🧮 We have added a set of payment project-specific screening frameworks in this issue. In addition to the traditional ones: Market value / FDV circulation ratio Unlock Revenue Tokenomics Protocol income I also focus on checking: ### ① Fee-bearing Volume What is the payment volume that actually generates handling fees? ### ② Take Rate For every $100 paid, how much money does the agreement make? ### ③ Token Necessity After payment increases, does Token have to be used? ### ④ Settlement Dependency Without this Token, can the payment be completed normally? ### ⑤ Are Regulatory Moat licenses, bank qualifications, and payment networks actual barriers? ### ⑥ Revenue-to-Token Conversion For every $100 earned by the protocol, how much money actually goes back to Token? ### ⑦ After Net Revenue GMV is very large, what is the real profit left? ### ⑧ Distribution Control Who controls the user and merchant entrances? ### ⑨ Loss Economics Who is ultimately responsible for bad debts, fraud, and settlement losses? ### ⑩ How much of the business data published by the Onchain Verifiability project can be independently verified? ━━━━━━━━━━━━━━ # 🏆 After three layers of screening, 3 ## are finally left 🥇 ZBCN|Zebec Network I define it as: ### **Crypto Payments Core Candidate** Zebec has really entered: Payroll Enterprise Clients Stablecoin Payments Card Merchant Spending And its most important advantage is not that "the business is real." Rather: ### **There is already an economic connection between the business and ZBCN. ** Product fees can form ZBCN Demand; Operating Revenue will be used for Market Buyback. At the same time, ZBCN has basically completed the planned unlocking. So it forms a relatively complete structure: **Business Growth** → **ZBCN Fee Demand** → **Operating Revenue** → **Market Buyback** Special explanation is required: ⚠️ Buyback ≠ Burn Currently, the repurchased assets mainly enter Locked Treasury / Institutional Custody and are not directly and permanently destroyed. So what I am optimistic about is: **The bridge between business growth and Token demand. ** Instead of packaging it as a "high repurchase yield Token". ━━━━━━━━━━━━━━ # 🥈 AMP|Flexa AMP is a very interesting high-odds candidate in this issue. Because AMP itself is not a payment currency. What it really bears is: # **Payment Collateral** When the consumer pays, the underlying asset may not have completed the final Settlement. But merchants can’t wait. So Flexa Capacity uses collateralized assets to provide instant security for payments. AMP is an important part of this mortgage system. This means: **Payment Volume ↑** → **Settlement Risk ↑** → **Collateral Requirement ↑** → **AMP Utility ↑** From a mechanism design perspective, it is even more straightforward than many Payment Tokens. Moreover, AMP’s current valuation is significantly lower than many popular payment projects. But it has a very big problem: # ⚠️ The real GMV transparency of Flexa is insufficient. We can confirm: Merchant POS payment network assets support the European expansion Capacity mechanism but there is still a lack of sufficiently transparent new GMV / Payment Volume data. So AMP is currently not: **"definitely undervalued."** but should be defined as: ### **The mechanism is very beautiful, but it is a high-odds reversal target that is waiting for verification by real business volume. ** ━━━━━━━━━━━━━━ # 🥉 ACH|Alchemy Pay The advantages of Alchemy Pay are completely different from those of AMP. It has built a very extensive: Fiat ↔ Crypto payment network. Covers: Bank cards Apple Pay Google Pay SEPA PIX UPI Mobile Money and many other traditional payment methods. What really made me increase the weight of ACH this time is: # **Alchemy Chain has been launched on Mainnet. **ACH is no longer just an ecological token for payment projects. It begins to bear: ### Gas / Transaction Fee Settlement At the same time, the new economic model also plans to use part of: Protocol Revenue for: ### Open Market ACH Buyback So ACH is establishing: **Payment Business** → **Alchemy Chain** → **ACH Gas** → **Protocol Revenue** → **Buyback** This new value capture path. But problems also exist: ⚠️ Long-term supply increase ⚠️ The actual scale of Buyback still needs to be verified ⚠️ The real payment usage of Alchemy Chain is still in the early stages, so I define it as: ### **Growth Payment Token. ** ━━━━━━━━━━━━━━ # 👀 TEL|Why didn’t I put it in the top three even though the bank is real? Telcoin Digital Asset Bank is real. eUSD has also been launched. This is a very strong regulatory and product progression. However: ### **Telcoin Network Mainnet has not yet been officially launched. ** Therefore, we cannot regard in advance: TEL Gas Validator Staking Network Fee as a large-scale token value capture that has already occurred. TEL is currently more like: ### **Pre-Mainnet strategic observation target. ** What really needs to be observed is: Can Telcoin Bank really import users and funds into Telcoin Network? If this bridge is built in the future, TEL's investment rationale will be significantly strengthened. ━━━━━━━━━━━━━━ # ⚠️ HUMA|Why do I not buy it temporarily even though it has the strongest business? This is one of the most important cases in this issue in my opinion. Huma already has a very large Payment Financing Volume. The business is real. The cost is also real. But the problem is: # **This money currently mainly flows to LP. ** Instead of: HUMA Holder. So even in the future: Payment Volume ×10 If the agreement rules do not change, what may happen is: ### **LP makes more money** instead of: ### **HUMA Holder gets more cash flow. **This is why: **Good project ≠ good Token. ** In the future, if HUMA really builds: Protocol Revenue → HUMA Buyback or: Real Fee → HUMA Staker then I will re-evaluate. But now, I choose to keep waiting. # 🎯 EP26 Final Conclusion After studying this issue, I think the most important thing about Crypto Payments is not: "Who supports Visa." Nor: "Who covers more than 100 countries." Nor: "Who handles billions of dollars a year." But three questions: ### ① Are these payment volumes real? ### ② How much money does the agreement really make from payments? ### ③ Did the money finally enter the Token economic system? If the third question cannot be answered, then: **The company may become more and more successful, but the Token may not become more and more valuable. ** ━━━━━━━━━━━━━━ 📌 **EP26 Final Highlights** 🔵 **ZBCN** - Crypto Payments Core Candidate 🟣 **AMP** - High Odds Reversal Candidate🟢 **ACH** - Growth Payment Token 🟡 **TEL** —— Pre-Mainnet Strategic Observation ⚪ **HUMA** —— Good Business ≠ Good Token at the moment
свежие новости
Более>>-
 老墨讲美股
2026-09-23 16:09
-
 Биток На всю котлету
2026-09-23 16:09
-
 为什么叫QQ
2026-09-23 16:09
-
 FAM Trading
2026-09-23 16:09
-
 绀香BTC合约计划
2026-09-23 16:09
-
 南宫交易日记
2026-09-23 15:16
-
 Hype Price - Hyperliquid Gems 💎
2026-09-23 14:56
-
 Michael De
2026-09-23 14:56
-
 CRYPTO GURU
2026-09-23 14:56
Рекомендуемые темы
-
- Деятельность китов Dogecoin
- Получите самую свежую информацию о деятельности китов Dogecoin с помощью нашего всестороннего анализа. Узнайте о тенденциях, закономерностях и влиянии этих китов на рынок Dogecoin. Будьте в курсе нашего экспертного анализа и будьте впереди в своем путешествии по криптовалюте.
-
- Майнинг Догекоин
- Майнинг Dogecoin — это процесс добавления новых блоков транзакций в блокчейн Dogecoin. Майнеры награждаются новыми Dogecoin за свою работу. В этой теме представлены статьи, связанные с майнингом Dogecoin, в том числе о том, как добывать Dogecoin, о лучшем оборудовании и программном обеспечении для майнинга, а также о прибыльности майнинга Dogecoin.
-
- Запуск космического корабля Spacex
- В этой теме представлены статьи, связанные с запусками космических кораблей SpaceX, включая даты запуска, детали миссии и статус запуска. Будьте в курсе последних запусков космических кораблей SpaceX с помощью этого информативного и всеобъемлющего ресурса.
-
- Король мемов: Dogecoin
- В этой теме представлены статьи, связанные с самыми популярными мемами, в том числе «Король мемов: Dogecoin». Memecoin стал доминирующим игроком в криптопространстве. Эти цифровые активы популярны по ряду причин. Они управляют самыми инновационными аспектами блокчейна.
Избранные статьи
Более>>- 1 北极Pablo硬币(APC):揭开地球的奥秘,一次预售
- 2 Dogecoin,Pepe和Shiba Inu的新高点在2025年,但这个加密货币可能会以10,000%的收益偷走该节目
- 3 唐纳德·特朗普总统宣布加密战略储备后,梅米硬币的道路起义(DUP)可以100倍
- 4 Dogecoin(Doge)价格预测:到2025年底,Meme硬币可以达到10美元吗?
- 5 卡达诺(Cardano)的查尔斯·霍斯金森(Charles Hoskinson)对比特币和狗狗币发表了一些著名的评论
- 6 云挖掘热潮:比特币,狗狗和对被动加密收入的追求
- 7 Grayscale、Dogecoin 和 ETF 首次亮相:Meme 币的新时代?
- 8 Rexas Finance(RXS)到2025年可能会激增10倍,超过Pepe(Pepe)
- 9 比特币交易员在Doge上赚了3000万美元,预测这笔0.0000002 AI代币的激增6,000% - 获得80%的奖金令牌
- 10 Dogecoin(Doge)价格预测:Meme Coin可能会升至0.27美元
Выберите валюту

US Dollar
USD

Chinese Yuan
CNY

Japanese Yen
JPY
South Korean Won
KRW

New Taiwan Dollar
TWD

Canadian Dollar
CAD

Euro
EUR

Pound Sterling
GBP

Danish Krone
DKK

Hong Kong Dollar
HKD

Australian Dollar
AUD

Brazilian Real
BRL

Swiss Franc
CHF

Chilean Peso
CLP

Czech Koruna KČ
CZK

Singapore Dollar
SGD
Indian Rupee
INR
Saudi Riyal
SAR
Vietnamese Dong
VND

Thai Baht
THB
Выберите валюту
-
US Dollar
USD-$

-
Chinese Yuan
CNY-¥
-
Japanese Yen
JPY-¥
-
South Korean Won
KRW -₩
-
New Taiwan Dollar
TWD-NT$
-
Canadian Dollar
CAD-$
-
Euro
EUR - €
-
Pound Sterling
GBP-£
-
Danish Krone
DKK-KR
-
Hong Kong Dollar
HKD- $
-
Australian Dollar
AUD-$
-
Brazilian Real
BRL -R$
-
Swiss Franc
CHF -FR
-
Chilean Peso
CLP-$
-
Czech Koruna KČ
CZK -KČ
-
Singapore Dollar
SGD-S$
-
Indian Rupee
INR -₹
-
Saudi Riyal
SAR -SAR
-
Vietnamese Dong
VND-₫
-
Thai Baht
THB -฿